Loan size and leverage
Loans from £100,000, with the maximum determined by the value and strength of the transaction. Typical maximum LTV: 75% residential, 70% commercial and 60% land with planning permission.
Specialist property finance
If you are urgently seeking bridging finance, it’s worth knowing what lenders are likely to require from you to push things ahead. As a specialist broker, Tiger Financial arranges bridging finance through a panel of over 300 lenders, so we can match your application to the criteria that suit it best.
Loans from £100,000, with the maximum determined by the value and strength of the transaction. Typical maximum LTV: 75% residential, 70% commercial and 60% land with planning permission.
Terms up to 24 months. Acquisition, refinance, auction purchase, refurbishment, development exit and planning-related transactions can be considered.
First charge security is usual; second charge bridging and equitable charges may be considered. Existing debt, available equity and any required first lender consent affect the structure.
Individuals aged 18+, UK limited companies, LLPs, SPVs and overseas borrowers can be considered. Lender requirements differ by ownership structure and residency.
CCJs, arrears and other adverse credit may be acceptable on suitable security. The nature, age and explanation of the credit issue matter; acceptance is lender-specific.
Interest may be rolled up, retained or serviced. Serviced interest requires evidence of affordability. Arrangement fees are typically 2%, with valuation and legal costs; some lenders charge an exit fee.
Availability varies across the panel; acceptance of a property category does not establish the terms for an individual asset.
Tiger arranges unregulated finance for business and investment purposes only. All facilities are subject to lender assessment.
Sale or refinance is the usual exit. The lender will assess whether the proposed repayment is credible within the term. A refinance exit may require evidence of income or mortgage eligibility.
The source of the deposit must be disclosed. Gifts, directors’ loans and intercompany funds require appropriate evidence; acceptance and documentation depend on the lender.
For refurbishment or conversion, lenders may require a track record, schedule of works and relevant approvals. Funding and monitoring arrangements depend on the scope of the works.
Property condition, occupancy and tenancy are material to the assessment. HMO licensing and any permissions for the intended use must be addressed.
The valuation basis and interest treatment affect the available cash. Automated valuations are restricted to eligible properties; otherwise a physical valuation may be required.
Company borrowing may require personal guarantees. Lenders differ on residency, ownership and corporate credit history; these should be established before an application is submitted.
Bridging loans
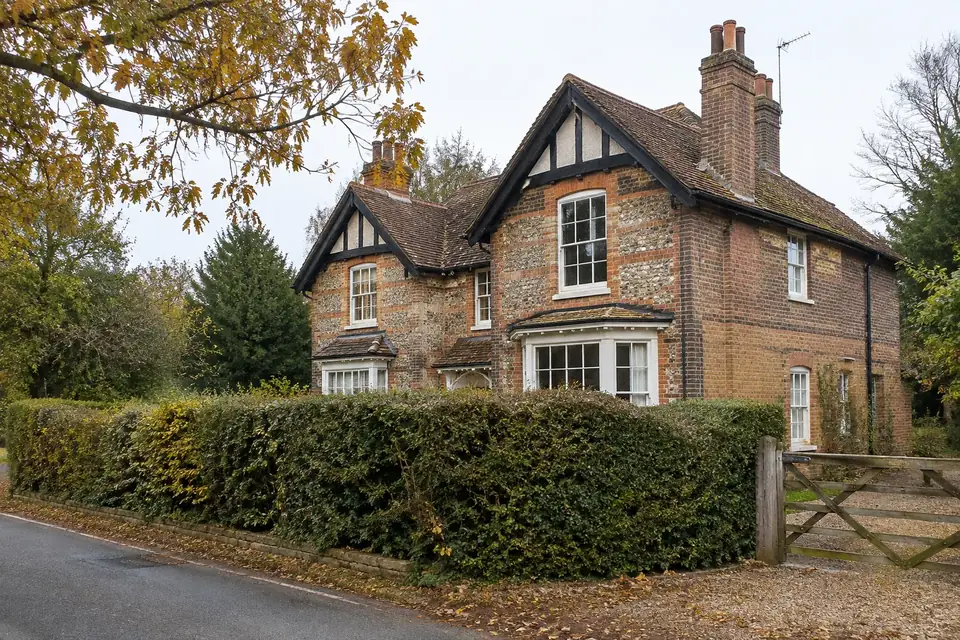
£1.28mWatford
Additional security kept a purchase moving despite lower valuations.
Read the case study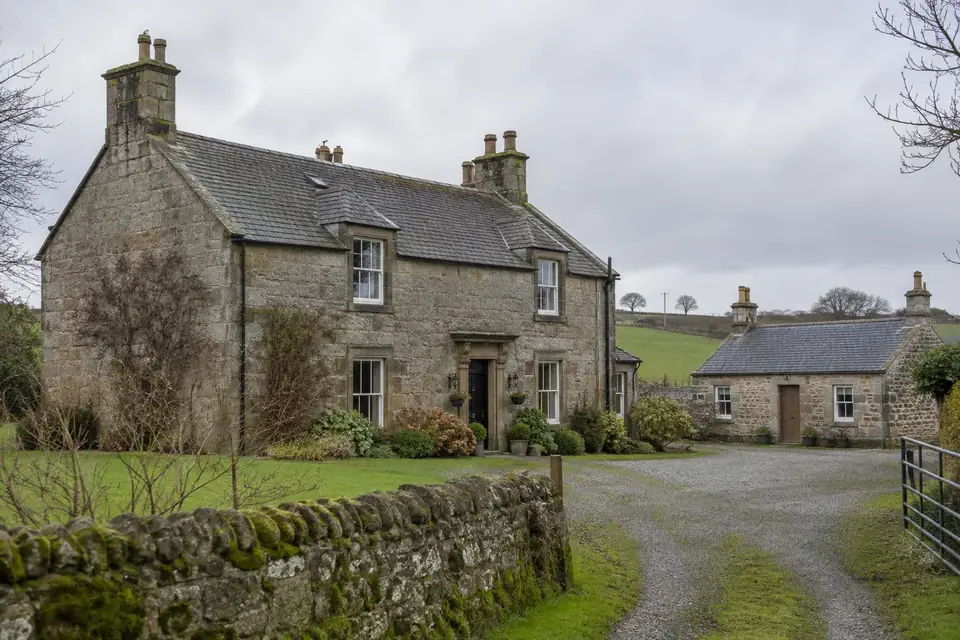
Bridging loans
£307,000Near Bathgate
A lender comfortable with short-term lets and third-party security.
Read the case study
Bridging loans
£136,500Hastings
A ground-rent variation accepted ahead of registration.
Read the case studyLet’s talk property
Get in touch now
We respond within one business hour.
Monday–Friday, 8am–6pm.